By Sally English Group
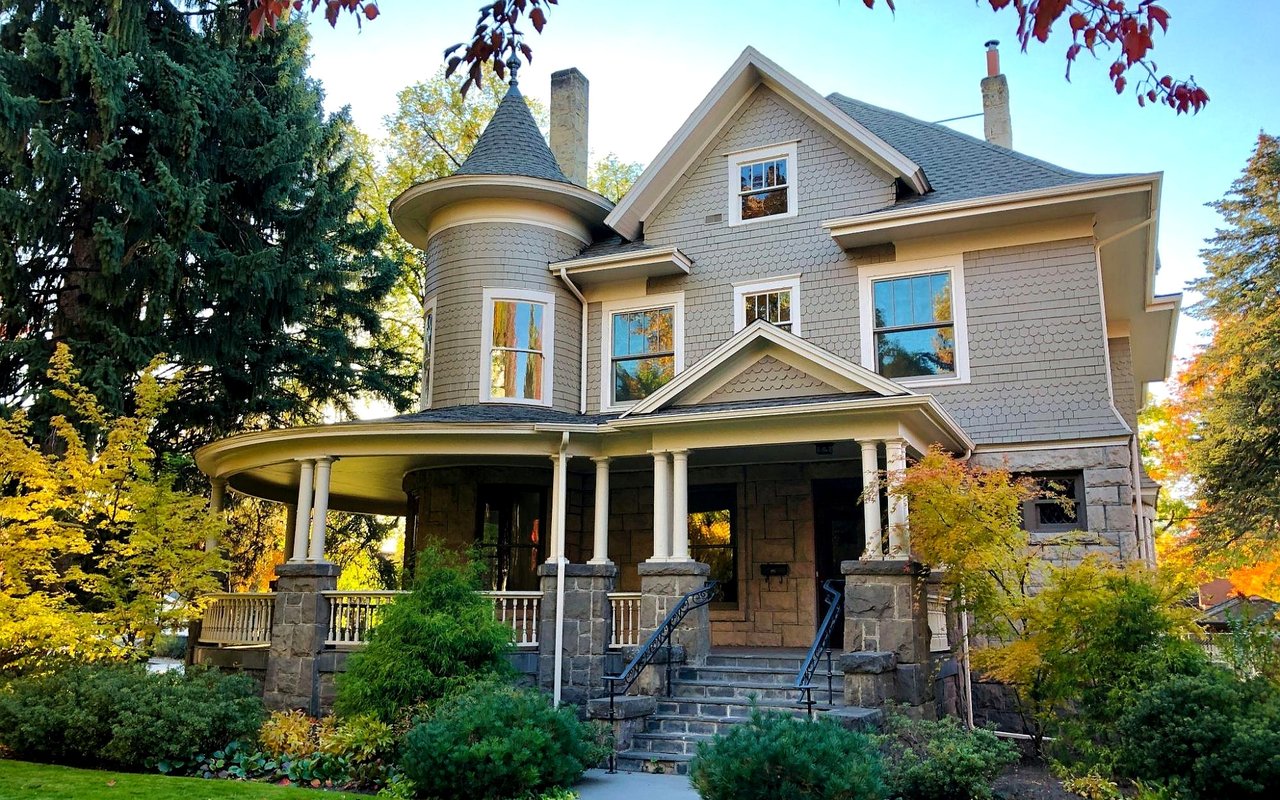
If you’re eyeing a Summit Avenue Victorian or a wooded estate in Sunfish Lake, the loan you choose matters almost as much as the home. We’ve guided luxury buyers through every kind of financing, and we know the right structure can save you real money. Let us walk you through the main types of mortgages so you can shop with confidence. Think of this as the conversation we’d have over coffee on Grand Avenue.
Key Takeaways
- Fixed and adjustable rates serve different timelines.
- Conforming loans stop at a federal ceiling.
- Jumbo mortgages fit most luxury purchases.
- Your plan to stay or sell shapes the best loan.
Fixed-Rate and Adjustable-Rate Mortgages
The first choice most buyers face is how your interest rate behaves. A fixed-rate mortgage keeps the same rate for the entire term, usually 15 or 30 years. That predictability is a comfort when you’re planning to stay in Mendota Heights for decades.
An adjustable-rate mortgage, or ARM, starts with a set rate and then changes on a schedule. A 7/6 ARM, for example, holds steady for seven years and then adjusts every six months. Buyers who expect to sell or refinance before the reset often use this structure to lower early payments.
Why This List Helps You Compare
- 30-year fixed: the lowest monthly payment and the most stability.
- 15-year fixed: higher payments, but far less interest paid over time.
- 5/6 or 7/6 ARM: a lower starting rate for a defined window.
- Rate caps: limits on how much an ARM can rise at each adjustment.
Make sure you ask any lender to show both options side by side. The better choice depends on how long you plan to live along the Mississippi River bluffs, not on a headline rate.
Conforming Loans and the Federal Ceiling
A conforming loan meets the standards set by Fannie Mae and Freddie Mac, which lets lenders sell it to investors. That backing usually brings competitive pricing and flexible terms. The baseline limit for a single-family home in most counties is $832,750 for 2026, up from $806,500 in 2025.
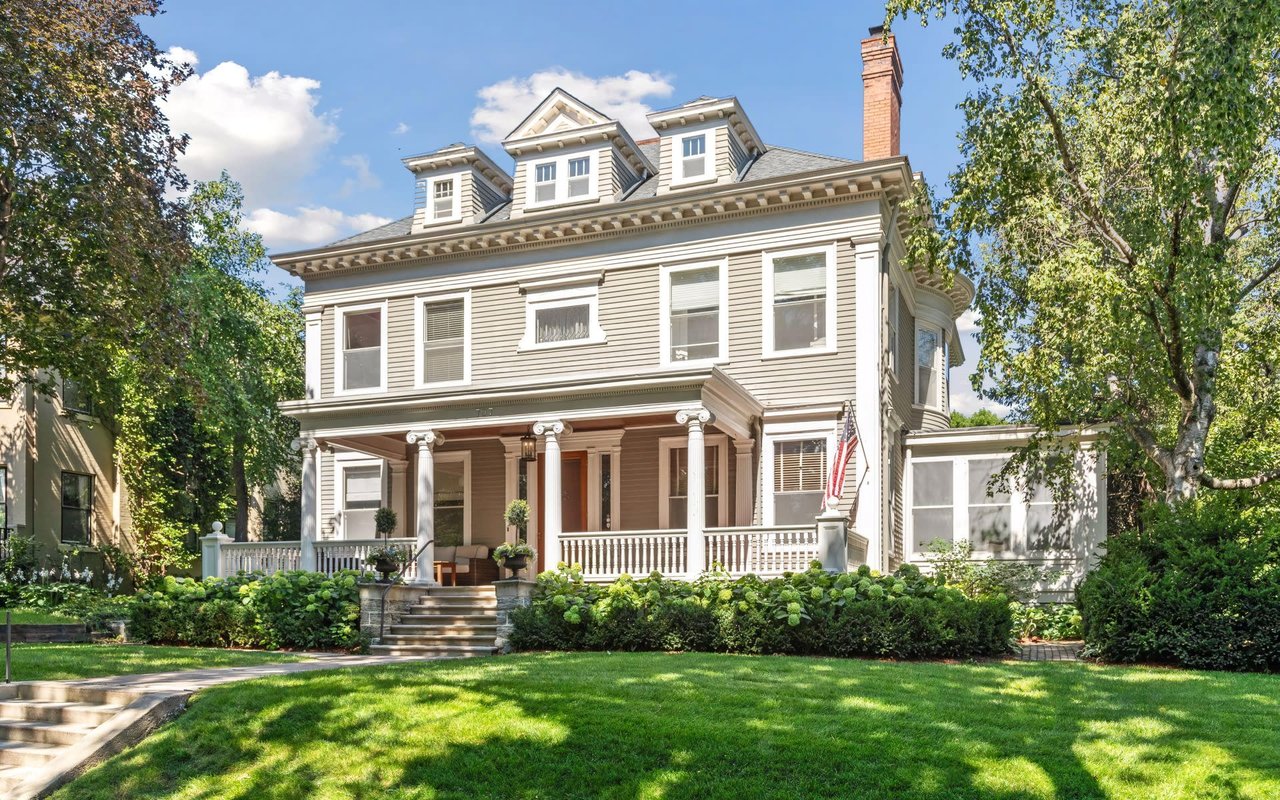
That ceiling matters in our market. A comfortable Edina home near 50th and France may fall under it, while many Summit Avenue and Sunfish Lake properties sit well above it.
What a Conforming Loan Typically Offers
- Lower down payments: often as little as 3 to 5 percent for qualified buyers.
- Broad availability: nearly every major lender offers them.
- Competitive pricing: investor backing keeps rates in a tighter range.
- Clear guidelines: credit and income rules are well documented.
Buyers purchasing a second home or a condo near Centennial Lakes Park often find a conforming loan is the top fit. Check the current limit before you write an offer, since it changes each year.
Jumbo Mortgages for Estate-Level Homes
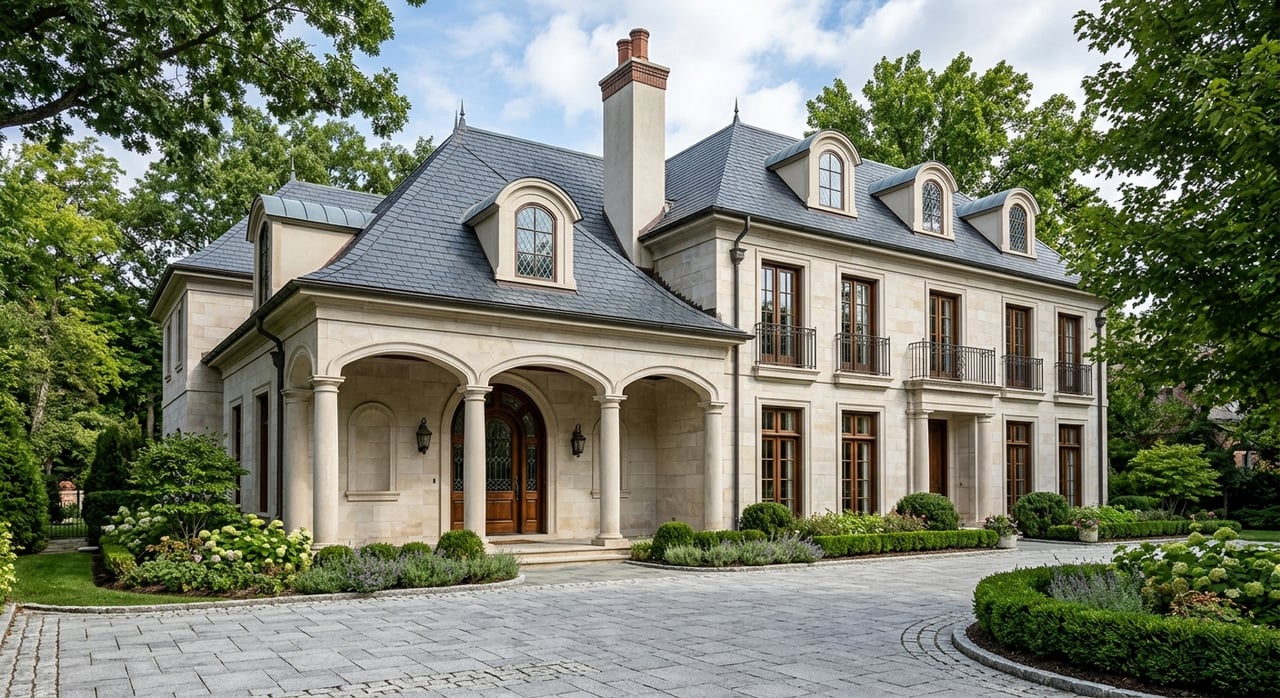
When the loan amount exceeds the conforming limit, you’re in jumbo territory. These loans carry no federal backing, so each lender sets its own rules. That’s why two banks can offer very different terms for the same Mendota Heights estate.
Jumbo lenders often look closely at credit, income documentation, and cash reserves. Many luxury buyers find the process smoother than expected when they prepare early.
What Jumbo Lenders Often Want to See
- A larger down payment: commonly 10 to 20 percent or more.
- Strong credit: higher scores usually earn better pricing.
- Cash reserves: months of payments held in liquid accounts.
- Complete documentation: tax returns, asset statements, and business records.
Some lenders also offer interest-only or portfolio jumbo products, which keep the loan on their own books and allow more flexibility. These suit buyers with complex income, like business owners or investors. Use a lender who regularly funds homes in the Twin Cities luxury range, because local experience shows in the underwriting.
Government-Backed and Specialty Options
FHA, VA, and USDA loans are backed by federal agencies and expand access for qualified buyers. FHA loans allow down payments as low as 3.5 percent with qualifying credit. VA loans can require no down payment for eligible veterans and service members.
These programs carry their own loan limits, so they rarely stretch to an estate in Sunfish Lake. They can work well for a first home in West Saint Paul or a condo near the Cathedral of Saint Paul.
When These Loans Make Sense
- FHA: lower credit thresholds and small down payments.
- VA: no down payment and no monthly mortgage insurance for eligible borrowers.
- Bridge loans: short-term financing to buy before your current home sells.
- Renovation loans: one loan covering purchase and updates.
Bridge financing deserves special mention. If you’re moving up from Edina to a larger Mendota Heights property, it can keep you from losing a home you love while your current one is on the market.
Matching the Loan to Your Timeline and Season
The best mortgage is the one that fits your plans. A buyer relocating for a few years has different needs than a family settling near Lilydale Regional Park for good. Seasonal timing matters too, since Minnesota’s winter slowdown can mean less competition and more room to negotiate.
Fall is a smart time to get pre-approved. Closing windows around the holidays can run long, so starting early keeps you ahead.
A Short Checklist Before You Choose
- Time in the home: short stays favor ARMs, long stays favor fixed rates.
- Cash position: decide how much to put down and how much to keep liquid.
- Tax planning: talk with your advisor about interest deductibility.
- Exit strategy: consider whether you may refinance or sell within a few years.
Frequently Asked Questions
What is the main difference between a conforming and a jumbo loan?
A conforming loan stays within the federal limit, which is $832,750 for most counties in 2026. A jumbo loan exceeds that amount and follows each lender’s own guidelines. Most luxury homes in Saint Paul and Sunfish Lake fall into jumbo range.
How much should I put down on a luxury home?
It depends on the loan type and your finances. Jumbo lenders often prefer 10 to 20 percent or more, while conforming loans can accept less. We’ll connect you with trusted local lenders so you can compare real numbers.
Should I choose a fixed rate or an adjustable rate?
If you plan to stay in the home for many years, a fixed rate offers peace of mind. If you expect to sell or refinance within five to seven years, an ARM may lower your early costs. We’ll help you weigh both against your timeline.
Contact Us Today
Choosing among the types of mortgages shouldn’t feel like guesswork. At Sally English Group, we pair you with the right financing partners so your offer is strong from day one. Whether you’re drawn to Edina, Saint Paul, Mendota Heights, or Sunfish Lake, we’ll make sure you understand every option.
Reach out to us at Sally English Group, and we’ll start with your goals, your timeline, and your must-haves. Together, we’ll find the home and the loan structure that fit your life.